Loan Against Property

Unlock Property Value
with Loan Against Property (LAP) Solutions

Unlock the value of your property with Loan Against Property solutions for business or personal needs.
Get expert guidance from DreamRise Capital.

Quick
Approval

Minimal
Documentation

Competitive
Interest Rates

Flexible Repayment
Options

Loan Amount
₹5 LAKHS TO ₹50 CRORE*
*T&C Apply

Interest Rate

8.55%* Per Annum

Onwards

EMI

depends on loan amount, tenure and interest rate.

Processing
Fees

Up to 1.5%* Of Loan Amounts

Loan Tenure

Up to 15 Years

Top Up / BT

After 6 Months

Interest Rate

8.55%* Per Annum

Onwards

EMI

depends on loan amount, tenure and interest rate.

Processing
Fees

Upvto 1.5%* Of Loan Amounts

Loan Tenure

Up to 15 Years

Top Up / BT

After 6 Months

What is a Loan Against Property?

A Loan Against Property is a secured loan where you pledge your residential or commercial property as collateral to obtain funds. It can be used for business expansion, education, medical expenses, debt consolidation, personal requirements and other financial needs.

Loan Against Property for Business

Business Expansion

Get funds to expand your business, purchase equipment or support working capital requirements.
Loan Against Property Financial Needs

Financial Flexibility

Access substantial funds against your property to meet a wide range of financial requirements.
Flexible Loan Repayment

Flexible Repayment Options

Choose a suitable repayment tenure according to your financial planning and repayment capacity.
Loan Against Property Interest Rate

Competitive Interest Rates

Explore suitable secured financing solutions through our lending partners.
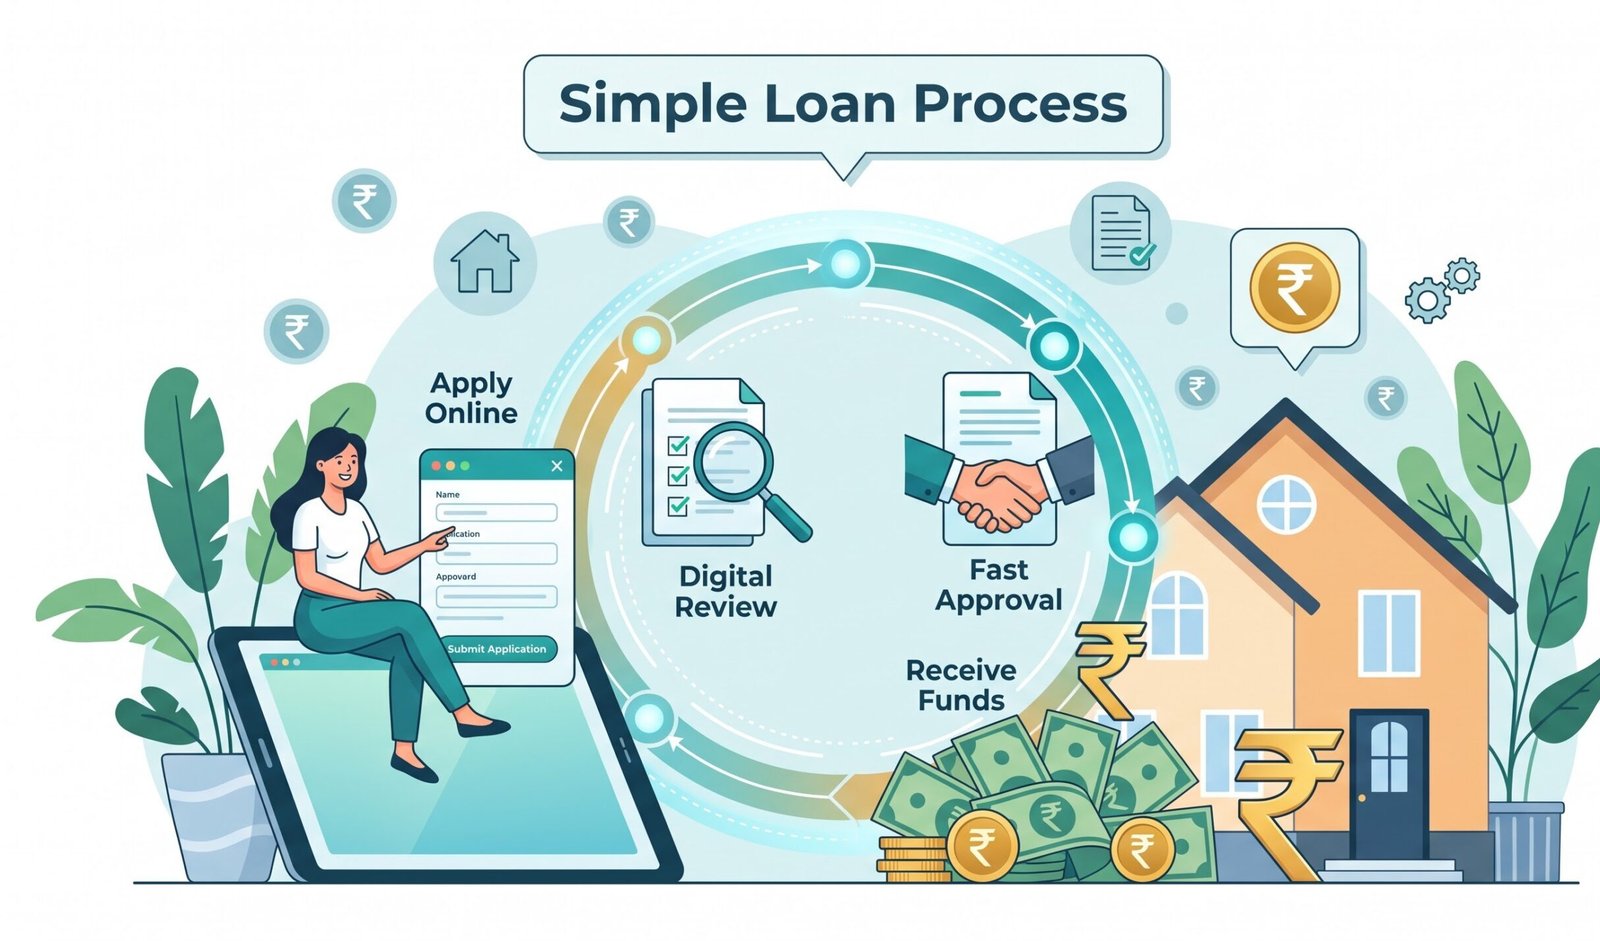
Quick Loan Process

Simple Loan Process

Get guidance through the application process with documentation support from our loan experts.
Multiple Uses of Loan

Multiple End Uses

Use the loan for eligible business, personal or other approved financial requirements.

Types Of Loan Against Property

✓

Residential Property LAP

Get a loan against residential properties such as houses, flats, and apartments. Suitable for business expansion, education, medical expenses, or other financial needs.

✓

Commercial & Industrial Property LAP

Avail funding against commercial or industrial properties such as offices, shops, warehouses, factories, and industrial units. Ideal for business expansion, machinery purchase, or working capital requirements.

✓

Self-Occupied, Rented & Leasehold Property LAP

Loan facilities may be available against self-occupied, rented, or eligible leasehold properties, subject to lender policies, property value, ownership, and documentation.

Features & Benefits of Loan Against Property (LAP)

Features:

  • High Loan Amount Access substantial funding based on the value of your property and lender eligibility.
  • Secured Loan Facility Your residential or commercial property can be used as collateral for the loan.
  • Flexible Repayment Tenure Choose a suitable repayment tenure as offered by the lender.
  • Competitive Interest Rates Secured financing may offer competitive interest rates compared with certain unsecured loan options.
  • Multiple End-Use Options Funds can be used for eligible business, personal, education, medical, or other permitted financial requirements.

Benefits:

  • Quick Processing Streamlined documentation and application processing can help reduce turnaround time.
  • Large Funding for Business Needs Suitable for business expansion, working capital, debt consolidation, or other eligible requirements.
  • Flexible Financial Planning A longer repayment tenure can help manage monthly cash flow.
  • Use Existing Property to Raise Funds Unlock the financial value of an existing property without selling it.
  • Suitable for Various Borrowers Salaried individuals, self-employed professionals, business owners, and eligible applicants may apply, subject to lender criteria.

Eligibility Criteria for Loan Against Property (LAP)

Eligibility Criteria:

  • Age: Applicant should generally be within the lender’s specified age range.
  • Income & Repayment Capacity: Stable and sufficient income to support the proposed loan repayment.
  • Employment/Business Stability: Salaried applicants should have stable employment, while self-employed applicants should have an established business.
  • Property Ownership: The applicant should own an acceptable residential, commercial, or other eligible property.
  • Property Documents: Clear and valid property ownership and legal documents are required.
  • Credit Profile: A satisfactory credit history and repayment record may improve loan eligibility.
  • Existing Obligations: Existing loans and monthly financial commitments are considered when assessing eligibility.
  • Property Valuation: The property must meet the lender’s valuation, location, and legal requirements.
  • Documentation: KYC, income, banking, and property-related documents must be submitted as required by the lender.

Documents Required for Loan Against Property (LAP) Application

Documents Required:

  • Identity Proof – PAN Card, Aadhaar Card, Passport, Voter ID, or Driving Licence.
  • Address Proof – Aadhaar Card, Passport, Utility Bill, or other valid address proof.
  • Income Proof (Salaried Applicants) – Latest salary slips and bank statements.
  • Income Proof (Self-Employed Applicants) – ITRs, financial statements, GST returns, and bank statements, as applicable.
  • Bank Statements – Recent bank statements showing income and financial transactions.
  • Property Documents – Sale deed, title documents, previous chain documents, and other relevant property papers.
  • Property Tax Receipts – Latest property tax receipts, where applicable.
  • Business Proof – GST registration, business registration, licence, or other applicable documents for self-employed/business applicants.
  • Existing Loan Documents – Details and statements of existing loans, if applicable.

Common Mistakes to Avoid When Applying for a Loan Against Property

✓

Not Checking Loan Eligibility & Credit Score

Applying for a Loan Against Property without reviewing your eligibility or CIBIL score.

1. Higher chances of loan rejection.
2. Lower credit scores may lead to higher interest rates.
3. Multiple loan applications can negatively impact your credit profile.

✓

Ignoring Total Loan Cost

Focusing only on the interest rate and ignoring other charges.

1. Processing fees can increase the overall loan cost.
2. Hidden charges may affect your budget.
3. Lower EMI doesn't always mean a cheaper loan.

✓

Choosing an EMI Beyond Your Budget

Opting for a higher loan amount without assessing repayment capacity.

1. Financial stress during emergencies.
2. Difficulty managing other household expenses.
3. Increased risk of EMI defaults affecting credit score.

Common Reasons for Loan Against Property Rejection

✓

Poor Credit Score & Credit History

A low credit score indicates higher repayment risk to lenders.
1. Credit score below the lender's eligibility criteria.
2. Frequent loan or credit card payment delays.
3. Loan defaults or settlements in the past.
4. High outstanding debt or excessive credit utilization.

✓

Insufficient Income & Financial Stability

Banks assess whether your income is sufficient to repay the home loan comfortably.
1. Monthly income below the required threshold.
2. High debt-to-income (DTI) ratio.
3. Unstable employment or frequent job changes.
4. Inconsistent business income for self-employed applicants.

✓

Property-Related Issues

Even if the applicant is eligible, the property must meet the lender's legal and technical requirements.
1. Incomplete or disputed property documents.
2. Unauthorized construction or approval issues.
3. Low property valuation compared to the loan amount requested.
4. Property located in a restricted or high-risk area.

Tips for Choosing the Right Loan Against Property

✓

Compare Interest Rates & Loan Costs

Choosing a home loan with the lowest interest rate can help reduce your overall repayment burden.

1. Compare interest rates from multiple banks and NBFCs.
2. Check processing fees and hidden charges.
3. Understand the difference between fixed and floating interest rates.
4. Calculate the total cost of the loan, not just the EMI.

✓

Evaluate Your Repayment Capacity

A home loan should fit comfortably within your monthly budget without affecting your lifestyle.

1. Assess your monthly income and expenses.
2. Choose an EMI amount that is easy to manage.
3. Maintain an emergency fund for unexpected situations.
4. Avoid borrowing more than you actually need.

✓

Check Loan Tenure & Eligibility

Selecting the right loan tenure and understanding eligibility criteria can improve approval chances and repayment flexibility.

1. Opt for a tenure that balances EMI affordability and interest cost.
2. Check your credit score before applying.
3. Keep income and property documents ready.
4. Ensure you meet the lender's eligibility requirements.

STEP-BY-STEP PROCESS TO
APPLY FOR A LOAN

🔗

Share Your Requirement

Tell us about your loan requirement and basic financial profile.

👤

Profile Understanding

Our team reviews the information provided to understand potentially suitable funding options.

📋

Explore Suitable Options

We help you understand available options from relevant Banks & NBFCs.

✔️

Documentation & Application

Get guidance on documentation and the application process.

🏦

Lender Assessment

The respective lender evaluates your application according to its policies and credit criteria.

💰

Sanction & Disbursement

After completion of lender formalities, the approved amount is disbursed by the lender.

Loan Against Property Calculator

Tips for Using the Online Loan Against Property Calculator

Most online loan calculators use the standard EMI calculation method. To calculate your EMI, you need to provide the principal loan amount, the interest rate, and the loan tenure.

Principal Amount
Interest Amount
₹
%
YrMo
Loan EMI
₹0
Total Interest Payable
₹0
Total Payment (Principal + Interest)
₹0
FAQ

Frequently Asked Questions

A Loan Against Property is a secured loan where you pledge your residential, commercial, or industrial property as collateral to obtain funds for personal or business needs.
Salaried individuals, self-employed professionals, business owners, traders, and companies owning eligible property can apply for a LAP.
The loan amount generally ranges from 50% to 75% of the property's market value, subject to eligibility and lender policies.
The repayment tenure can range from 5 to 20 years, depending on the lender, loan amount, and borrower profile.

Turn Your Property Into Financial Opportunity?

Get the right financial support to meet your business, personal, or expansion needs using your property.

Scroll to Top